
What is a Good Overhead Ratio for a Nonprofit? (And Why That’s Not the Right Question)
We’re often asked, “How much should we be spending on overhead costs?”
The truth is that there isn’t a universal answer. Many nonprofits choose to minimize any expenses other than direct program expenses, an approach epitomized by a statistic stating what percent of every dollar goes toward the mission.
They do that because the old wisdom was that if dollars were going toward overhead, that meant they weren’t going toward the mission. That’s of course not true. All organizations have overhead.
The tension grew to the point that the term “nonprofit starvation cycle” appeared. The heads of the three leading sources of information about charities — GuideStar (now Candid), Charity Navigator, and BBB Wise Giving Alliance — published an open letter in 2013 addressed to the donors of America, and the website “The Overhead Myth” followed.
The good news is that their efforts brought the conversation to light and influenced many people who work in the nonprofit sector.
The challenge is that donors haven’t caught up, which is why leaders like you are still asking this question, trying to find the magic number that makes you more competitive for funding.
So, what do you do about your overhead?
The three categories of nonprofit expenses
Nonprofit expenses can be divided into three distinct categories: program, fundraising, and administrative expenses.
Program expenses are directly related to carrying out your nonprofit’s mission and result in goods or services being provided. For example, expenses to run a camp, teach a class, put on a performance, award a scholarship, or deliver food or clothing to the underserved are all considered program expenses.
Fundraising expenses, on the other hand, include costs for promoting and conducting fundraising campaigns, maintaining donor lists, preparing acknowledgment letters, holding special events, and any other activities that involve soliciting contributions.
Administrative expenses apply to your overall operations and management. For example, the costs of board of directors’ meetings, committee meetings, general legal services, accounting, insurance, and bookkeeping.
Before we go on, note these classifications come from the IRS, and the IRS does not require you to spend any specific portion of your income on each category. It just wants you to report how you spent your money.
These classifications become an issue when they get published as a measure of an organization’s health or performance.
Donors still flinch at overhead
While platforms like Charity Navigator may have stopped rewarding low overhead, many donors haven't. A 2021 study in Nonprofit and Voluntary Sector Quarterly shows how strong that reaction is, and how to reduce it.
Researchers asked 1,482 people who had donated within the past five years a simple question: after a natural disaster, to which of two relief organizations would you give $100? Organization A focused on immediate relief. Organization B focused on long-term rebuilding. The mission descriptions never changed. Only the financial information did.
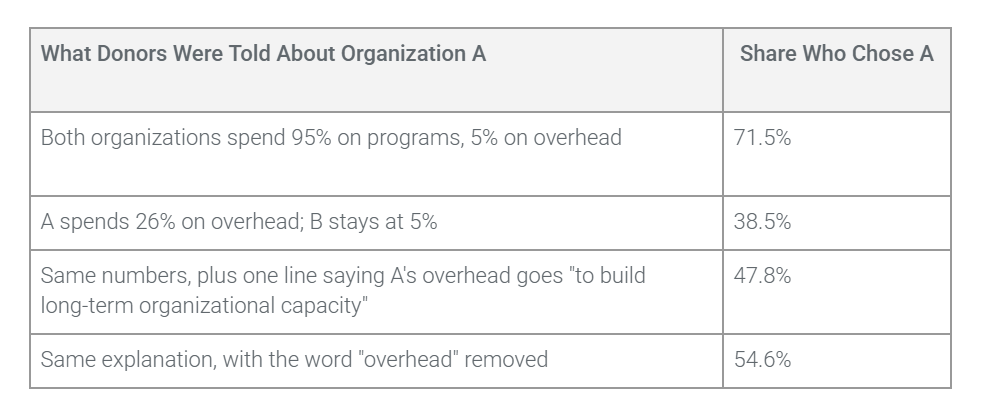
The researchers chose 26% deliberately. It's above the 19% the average American donor considers reasonable to spend on overhead, and close to the 28% donors believe a typical charity actually spends, according to a 2018 Grey Matter Research survey the authors cite.
45% of donors said the program/overhead split was their main reason for choosing the lower-overhead organization. Adding one line of explanation about overhead cut this group down to 31%. Removing the word "overhead" cut it to 24%.
What do they think overhead is?
After making their choice, respondents were asked to give an example of an overhead expense. Nearly half couldn't name one, either answering “I don't know“ or naming costs that are actually program expenses. Those who understood overhead to some degree punished the higher-overhead organization more than those who couldn’t give an example.
The donors who pictured something specific reacted most strongly when they pictured people. Among respondents who named salaries, wages, or staff, support for the higher-overhead organization fell from 76.7% to 20.8% once its overhead was disclosed — the steepest drop in the study.
An explanation helped this group: support rose to 34.2% when overhead was described as building capacity. Removing the word "overhead" moved only the donors who had pictured costs like rent and utilities.
For donors who picture salaries, a new label isn't enough. You’re going to need an explanation of what the people make possible.
What that means for the people you need
You can't control a donor's first reaction to a ratio, but you do control what appears next to it. Consider including a short statement of purpose where overhead figures show up.
Going further, use a fractional approach to staffing. Start by breaking down your goals so you know what skills you need and how much you need them. Then group those skills together by level (entry, director, etc.) and align people to those roles.
That builds the purpose of every person right from the beginning. What’s more, you have the work to show you’ve right-sized all your investments. If a role only required 10 hours a month, you hired a fractional professional to fill it.
Now, while this research is helpful, stay reasonable. Participants in the study made a hypothetical choice rather than giving real money. The scenario involved disaster relief only. And framing narrowed the gap without closing it: even with the best framing, 54.6% chose the higher-overhead organization, compared to 71.5% when both organizations reported the same low overhead.
That’s why it still matters that you categorize your people costs correctly. For instance, if the main purpose of your organization is to award scholarships and you have an administrative assistant who is managing your scholarship program, i.e., receiving applications, responding to applicants, securing missing materials, typing award letters, then these tasks would be categorized under “program.” If that same assistant is accepting and posting entries for your golf tournament, the resources spent on those tasks would be categorized under “fundraising.”
Evaluate the positive impact of overhead
Make no mistake: nonprofits are accountable to the community at large. But nonprofits will have overhead, including the costs of having people to do the work that keeps the organization running sustainably.
Rather than judging the worth and impact of a nonprofit by how little it spends on overhead, perhaps we evaluate how much impact this overhead ultimately has on the success of the organization and the ability of the nonprofit to meet its mission.
Source: Qu, H., & Levine Daniel, J. (2021). Is “overhead” a tainted word? A survey experiment exploring framing effects of nonprofit overhead on donor decisions. Nonprofit and Voluntary Sector Quarterly, 50(2), 397–419. https://doi.org/10.1177/0899764020959475. Free full text (accepted manuscript, PDF).